The average M&A deal takes about six months to close. That feels like a lifetime until you are the one answering the 47th question about a contract signed in 2016. Most legal teams do not fail because they lack lawyers. They fail because they are not ready when the data request hits.
Here is the honest version: you can cut days off your review timeline by preparing before the buyer asks for anything. This guide shows you exactly what to organize, who to brief, and what habits to kill before your next deal starts. If you take one thing from this, let it be this: preparation is the difference between a review that drags for months and one that closes early.
Why Most Legal Teams Get Caught Off Guard
In-house legal teams are busy. You are handling contracts, compliance questions, employment issues, and the occasional emergency that has nothing to do with the deal sitting on your desk. When an acquisition opportunity appears, the instinct is to jump straight into collecting documents. That is a mistake.
The first problem is ownership. Nobody gets assigned as the deal captain. The workload spreads across three or four attorneys who each handle a slice, and nobody tracks what has actually been produced. The second problem is timing. Requests arrive faster than you expect, and your team is already at max capacity. The third problem is content. You have no idea what is in your own shared drives because nobody has organized them in years.
Here is the thing: buyers have run this process dozens of times. They know what they want. If your side fumbles the first request, it signals disorganization, and that slows the whole negotiation down. Per guidance from the American Bar Association, a well-managed legal review process is a core expectation in any corporate transaction. The buyer is not just looking at your documents; they are gauging how you operate.
The buyer is not just looking at your documents; they are gauging how you operate. That same attention to consistency applies to your broader business presence, where ways to build a strong brand online can help reinforce credibility before a potential buyer begins a deeper review.
What to Organize Before the First Request Arrives
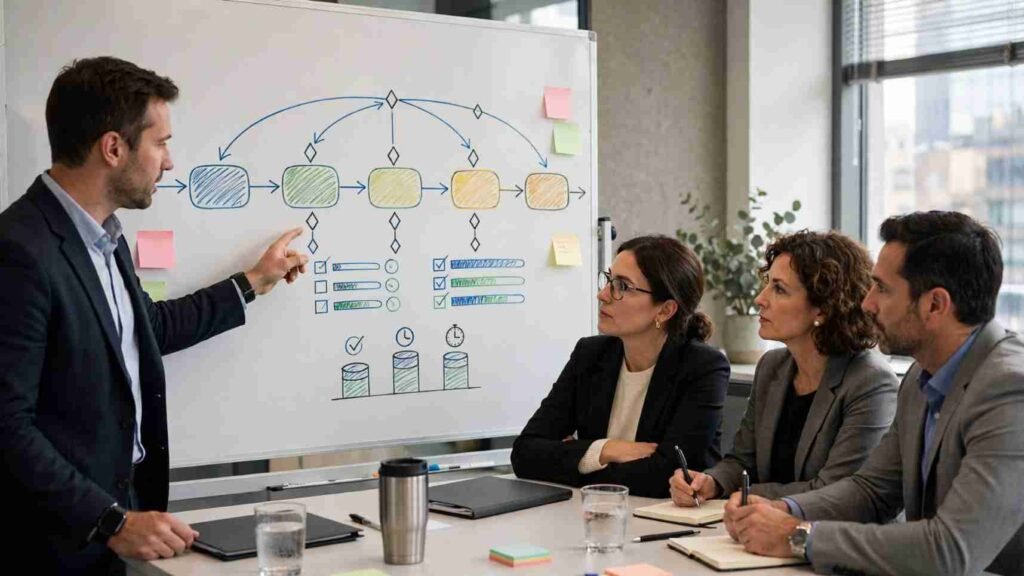
You cannot prepare for every random question, but you can prepare for the 80 percent that always come. Start with the standard categories every buyer requests in a legal due diligence review.
Corporate records. Pull your certificate of incorporation, bylaws, board minutes, and shareholder consents. Make sure they are current and signed. A surprising number of companies discover their ownership records are incomplete when the buyer asks for a full cap table.
Material contracts. Gather your top customer agreements, vendor contracts, leases, and partnership deals. Have a summary sheet ready that explains the commercial terms in plain English rather than legalese.
Employment agreements. Collect offer letters, non-compete clauses, and any documents related to equity compensation for key staff.
Litigation history. Prepare a list of past and pending cases. Detail matters less than completeness. If you hide a lawsuit and the buyer finds out later, trust breaks down.
Intellectual property. Track down your trademarks, patents, and domain registrations. Verify who actually owns them, because transfers sometimes lag behind reality.
Now, here is the part most people skip: organize everything into a single logical structure before the deal starts. You do not need to upload anything yet. You just need to know where every document lives. When the data room opens, you can populate it in hours instead of weeks.
The Index Is Your Best Friend
A data room index is just a map of your files. It sounds boring. It is not.
A good index lists the folder names, the document types inside each one, and the date ranges covered. When a buyer asks for “all board minutes from 2021 to 2024,” you should be able to point them to the exact folder without searching your entire drive.
That speed creates confidence on the buyer’s side. The same principle applies to how a company presents itself externally, including enhancing brand visibility with promotional flags and banners as part of a broader effort to maintain a consistent and recognizable brand presence.
It makes them think your company runs smoothly, and that impression carries into the negotiation phase.
Build your index around how the buyer will think. They care about corporate structure, financial performance, contracts, employees, and risk. Use those labels for your folders instead of internal department names that mean nothing to an outsider. If your finance team uses a folder called “MJ & stuff” for material contracts, rename it before anyone sees it.
For public companies, this discipline is even more critical. The Securities and Exchange Commission holds public issuers to strict disclosure standards, and your due diligence materials often inform those filings. A messy process risks more than a slow deal; it risks a compliance problem.
Five Mistakes That Slow Every Review Down
You can avoid most delays by recognizing these five recurring errors before they happen.
Mistake one: Scanning everything in the wrong order. Your team’s instinct is to scan the newest files first because they are easiest to find. The buyer, however, wants the historical records first to understand how the company evolved. Scan your oldest contracts first, and your reviewers will stop emailing you for the basics within the first week.
Mistake two: Ignoring version control. You have three versions of the same customer agreement sitting in different folders. Your team is going to upload the wrong one. Label every file with a version number and date at the start, and you eliminate half the confusion before it starts.
Mistake three: Redacting inconsistently. If you remove sensitive terms from one contract, check the other fifteen that contain the same language. Reviewers compare documents across the set. Inconsistency triggers follow-up questions that cost you days.
Mistake four: Forgetting to resolve the team. Your best transactional attorney is also the one who handles general litigation. Who covers their desk while they work the deal? Assign backup coverage before the room opens, not when the first conflict appears.
Mistake five: Overthinking security. You need to protect confidential information, but you do not need to make it impossible for the buyer to view anything. Paralysis slows the review, and a buyer who cannot access documents quickly becomes a buyer who walks away. If you want to avoid the classic pitfalls entirely, you can read about common mistakes and see how other teams have handled these issues in practice.
Building the Review Timeline That Works
Most teams underestimate how long the review takes by about 40 percent. The buyer’s counsel needs time to read, discuss, and ask follow-ups. Your team needs time to answer without dropping their regular work.
Set a realistic schedule at the start. A standard data room review for a mid-sized company runs between three and six weeks of active document production, not counting negotiation time. Break that into phases: production, first-round questions, re-review, and final confirmation. The Project Management Institute emphasizes that phased project planning reduces rework significantly, and due diligence is no exception.
Create a shared tracker everyone can see. List every document request, who owns it, and when it is due. Review that tracker every morning for ten minutes. If something is three days late, escalate it before it becomes a week late.
Set hard response time targets. Two business days for straightforward requests, five days for complex ones. Those targets sound tight, but they keep the deal moving. A motivated buyer sends new questions every week. Your tracker is what keeps those questions from spiraling out of control.
Keep the Momentum After Submission
Submitting your documents is not the finish line. The buyer’s counsel will review everything, find gaps, and come back with a second round. Budget for it. The second round is usually smaller, but it demands accuracy because the buyer is now cross-checking details.
The second round is usually smaller, but it demands accuracy because the buyer is now cross-checking details. At this stage, the broader features that enhance business appeal can also influence how the buyer views the company beyond the documents themselves.
Appoint one person as the single point of contact for the entire review. Every buyer email goes to them. They triage requests, assign internal owners, and track progress. This is not a glamorous job, but it prevents mixed messages from derailing the deal.
Maintain a living list of every question the buyer asks. When the same question appears twice, that signals a gap in your documentation. Fix it proactively instead of answering the same thing repeatedly.
Conclusion
Finally, schedule a debrief after the deal closes. Write down what slowed you down and what worked well. That list becomes your playbook for the next transaction. Deals do not get simpler, but your preparation can get smarter.
Nobody enjoys the stress of due diligence, but the discomfort is temporary. A clean, well-organized review builds trust with the buyer and shortens the path to closing. Ask yourself honestly: if a buyer requested your full corporate record tomorrow, could your team assemble it within a week? If the answer makes you uncomfortable, that discomfort is your signal to start organizing today.